In South Africa, funeral insurance is one of the most common forms of cover because death does not only bring grief — it also brings immediate costs, family responsibilities and cultural expectations. When someone passes away, the family may need money quickly for the coffin, burial or cremation, transport, catering, family travel, tombstone costs, airtime, documents and other arrangements. So, the real question is not only, “Do I need funeral insurance?” The better question is: “If I passed away, would my family have enough money available immediately to bury me with dignity without borrowing?”
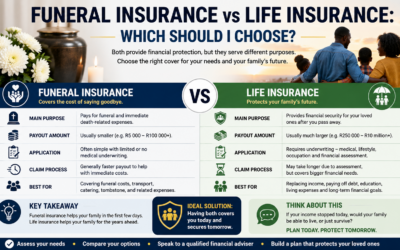
Funeral insurance, also called funeral cover or a funeral policy, is designed to pay a lump sum when an insured person dies. It is different from life insurance because funeral cover usually focuses on short-term death-related expenses, while life insurance focuses on long-term financial protection for dependants. Funeral cover is often easier to apply for, may have limited medical underwriting, and is generally designed to pay faster once all required claim documents are submitted.
Why Funeral Insurance Matters in South Africa
Funerals in South Africa can carry deep emotional, cultural and family significance. For many families, a funeral is not just a private event; it is a community gathering and a final act of honour. But these expectations can create financial pressure, especially when death is sudden and savings are limited.
ASISA reported that its member life insurers settled 94.1% of death claims in 2025 across individual life, credit life, funeral and universal life policies, paying R44.2 billion to beneficiaries. This shows how important death-related cover remains in helping families manage the financial impact of losing a loved one.
When Funeral Insurance Is Worth Having
Funeral insurance is worth considering if your family would struggle to raise money quickly for funeral costs. It can also be useful if you are responsible for elderly parents, a spouse, children or extended family members who may not have their own cover.
It may be especially helpful if:
- You do not have enough emergency savings.
- Your family would need cash within days after death.
- You want to cover parents or extended family members.
- You want to avoid your loved ones borrowing money.
- You have cultural or family funeral obligations.
- You do not yet qualify for, or cannot afford, larger life cover.
- You want a simple policy for immediate funeral-related expenses.
The value of funeral cover is not only the payout. It is the relief it gives your family during a painful and stressful time.
When You May Not Need Funeral Insurance
You may not need separate funeral insurance if you already have enough accessible savings specifically set aside for funeral costs, or if your existing life insurance includes a funeral benefit that pays quickly. You may also be less dependent on funeral cover if your employer, union, pension fund or group risk scheme provides a funeral benefit.
However, you must check the details carefully. Some employer or group funeral benefits end when you leave the job. Some benefits may be limited to the employee only. Some may not cover extended family. Others may not pay quickly enough for immediate funeral expenses.
Do not assume you are covered. Confirm the amount, who is covered, when it pays, what documents are required and whether the benefit continues if your employment changes.
Funeral Insurance vs Life Insurance
Funeral insurance and life insurance are not the same thing. Funeral cover helps your family with the cost of saying goodbye. Life cover helps your family continue financially after you are gone.
A funeral policy of R20 000, R50 000 or R100 000 may help pay for the funeral, but it will not replace years of income. If you have children, a spouse, a bond, vehicle finance, personal loans or people who depend on you financially, funeral insurance alone is usually not enough.
Life insurance should be considered if your death would leave your family unable to pay monthly expenses, school fees, debt or long-term financial commitments. Funeral cover deals with the first few days or weeks. Life cover deals with the years that follow.
What About Burial Societies?
Many South Africans belong to burial societies, stokvels or community-based funeral arrangements. These can be valuable because they provide social support, shared responsibility and practical assistance. But they should still be reviewed like any other financial arrangement.
Ask important questions: How much will be paid? How quickly will it pay? Who controls the funds? What happens if the group has financial problems? Are all family members covered? Is there a written constitution or agreement? Is the benefit enough for today’s funeral costs?
A burial society can form part of your plan, but it may not replace formal funeral insurance if certainty, contract terms and regulated claims processes are important to you.
Waiting Periods Matter
One of the most important things to understand about funeral insurance is the waiting period. Many funeral policies have a waiting period for death from natural causes. This means the policy may not pay if the insured person dies from natural causes during that waiting period.
South African regulations limit waiting periods for funeral or microinsurance policies for natural-cause death benefits to no more than the shorter of one quarter of the policy term or six months. Some insurers also apply a waiting period for suicide, and accidental death may be treated differently depending on the policy. Always read the policy wording before relying on the cover.
Why Claims Can Be Declined
Funeral claims are not automatically guaranteed. A claim may be declined if the policy lapsed, the insured person died during the waiting period, premiums were unpaid, the person was not properly covered, fraud occurred, exclusions applied, or the required documents were not submitted.
ASISA notes that declined life insurance claims are often linked to material non-disclosure, meaning important information was not properly disclosed when the policy was taken out. For funeral policies, waiting periods, policy lapses and incorrect details are common practical issues families should avoid.
This is why it is important to keep the policy active, pay premiums on time, update beneficiaries and ensure family members know where the policy documents are kept.
How Much Funeral Cover Is Enough?
There is no single amount that works for every family. The right amount depends on the type of funeral your family expects, your cultural obligations, location, transport costs, number of people likely to attend, burial or cremation preferences, catering, tombstone expectations and family support needs.
A practical approach is to estimate the full cost of a realistic funeral, then compare that amount with your savings, burial society benefits, employer benefits and existing policies. Do not over-insure for emotional reasons, but also do not under-insure and leave your family short.
Remember, funeral cover should be affordable. A policy only helps if you can keep paying the premium.
What Should You Check Before Buying Funeral Insurance?
Before taking funeral cover, check:
- The exact monthly premium.
- The cover amount.
- Who is covered.
- Waiting periods.
- Exclusions.
- Claim documents required.
- Whether premiums increase.
- Whether cover reduces at older ages.
- Whether the insurer and adviser are properly licensed.
- What happens if you miss a premium.
- Whether children, parents or extended family members have legal cover limits.
The FSCA regulates and supervises the conduct of financial institutions in South Africa, so consumers should be careful to deal with properly authorised providers and verify who is actually underwriting the policy.
So, Do You Really Need Funeral Insurance?
You probably need funeral insurance if your family does not have enough accessible cash to pay for your funeral immediately. You may also need it if you want to protect your loved ones from debt, panic and last-minute fundraising during a time of grief.
But funeral insurance should not be your only form of financial protection. If you have dependants, debt or people relying on your income, you should also consider life insurance. Funeral cover pays for the funeral. Life cover protects the family’s future.
Final Thoughts
Funeral insurance is not about expecting death. It is about planning responsibly for an event every family will face one day. In the South African context, where funerals can carry cultural, emotional and financial weight, funeral cover can be a practical way to protect your loved ones from immediate financial pressure.
If your family would need to borrow, collect donations or sell assets to bury you, funeral insurance is worth considering. If you already have enough savings and strong life cover with a quick funeral benefit, you may not need a separate policy. The right answer depends on your family, your budget and your responsibilities.
Before choosing a policy, speak to a qualified financial planner who can help you compare funeral cover, life cover, group benefits, burial society support and your overall financial plan. The goal is simple: when grief comes, your family should have space to mourn — not panic about money.