When choosing healthcare cover in South Africa, you may encounter the terms medical aid and medical insurance. Although they sound similar, they are fundamentally different products. Medical aid generally provides broader healthcare funding and must include certain legally prescribed benefits, while medical insurance usually offers limited cover or a predetermined payout for specified healthcare events.
What is medical aid?
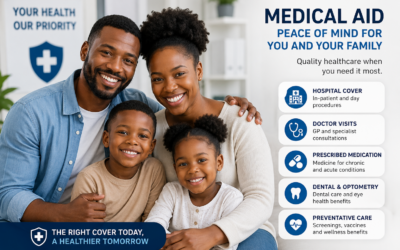
Medical aid refers to membership of a registered medical scheme regulated under the Medical Schemes Act. Depending on the option selected, it may cover expenses such as private hospital treatment, specialist consultations, doctors’ visits, medicine, dentistry, optometry and chronic healthcare.
Registered medical schemes must provide Prescribed Minimum Benefits (PMBs). These include emergency medical conditions, a defined list of medical conditions and specified chronic diseases. Scheme rules, designated service providers, treatment protocols and pre-authorisation requirements may still apply.
Open medical schemes must accept applicants who can afford the applicable contributions, regardless of their age or health. However, schemes may impose lawful waiting periods and late-joiner penalties in certain circumstances.
Medical aid contributions are generally determined by the option selected, income band where applicable and number of dependants—not by an individual member’s medical risk. Members on the same option and income category generally pay the same contribution structure.
What is medical insurance?
Medical insurance is an insurance policy that provides benefits for healthcare events listed in the policy. It may pay a fixed amount for hospitalisation, an accident, a specified procedure or certain day-to-day healthcare services.
Unlike medical aid, medical insurance does not have to provide the comprehensive PMB protection applicable to registered medical schemes. Its benefits are defined by the policy and may be subject to monetary limits, waiting periods, exclusions, provider networks and a restricted number of consultations or treatments.
Some medical insurance products pay the policyholder a predetermined cash amount rather than settling the full healthcare provider’s account. If the actual medical bill exceeds the policy benefit, the policyholder remains responsible for the shortfall. The Council for Medical Schemes therefore cautions that health insurance offers partial and conditional protection and must not be presented as a substitute for medical-scheme membership.
Medical aid versus medical insurance
| Feature | Medical aid | Medical insurance |
|---|---|---|
| Main purpose | Funds qualifying healthcare expenses according to scheme rules | Pays specified benefits for insured healthcare events |
| Regulation | Medical Schemes Act | Insurance legislation and applicable policy regulations |
| PMB protection | Mandatory | Not generally required |
| Benefit structure | Based on the chosen scheme option and tariff rules | Based on fixed amounts, stated services or policy limits |
| Acceptance | Open schemes must generally accept applicants | Applications and premiums may be assessed under the policy’s underwriting rules |
| Contributions | Generally community-rated within the same option and category | May be risk- or age-rated, subject to applicable rules |
| Waiting periods | May include general and condition-specific waiting periods | May also include waiting periods and exclusions |
| Cost | Usually higher because the protection is broader | Usually cheaper because the protection is more limited |
Is medical insurance the same as a hospital plan?
The term “hospital plan” can create confusion. A medical scheme may offer a hospital-plan option that covers qualifying in-hospital treatment and PMBs. An insurer may also offer a hospital cash or hospitalisation policy that pays a fixed benefit when the insured person is admitted to hospital.
These products do not provide identical protection. Before buying a “hospital plan,” establish whether it is a registered medical-scheme option or an insurance policy, and confirm whether it settles eligible medical expenses or merely pays a predetermined cash benefit.
What about gap cover?
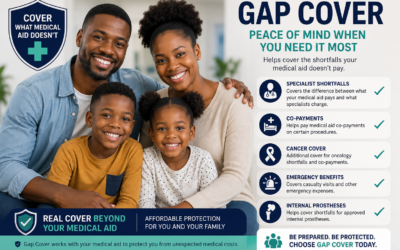
Gap cover is a form of supplementary insurance intended to help medical-scheme members with certain shortfalls when healthcare professionals charge more than the scheme tariff. It is not medical aid and cannot replace medical-scheme membership. Cover remains subject to policy limits, exclusions and qualifying events.
Which option should you choose?
Medical aid may be more suitable if you need broader private healthcare protection, cover for chronic conditions or stronger protection against major hospital costs. Medical insurance may be useful when affordability is the primary concern and you understand that the cover is narrower and subject to specific limits.
When comparing products, do not focus only on the monthly cost. Consider your health needs, dependants, chronic medication, hospital network, exclusions, waiting periods, co-payments and the maximum amount the product will pay. Read the benefit schedule carefully and seek professional advice where necessary.
Ultimately, medical aid and medical insurance can both play a role in a healthcare plan, but they are not interchangeable. Knowing exactly what will be covered and what you may still need to pay yourself can protect your health and finances when medical care becomes necessary.